Hong Kong two-tiered profits tax: 8.25% on the first HK$2M, worked examples and 2025/26 filing deadlines
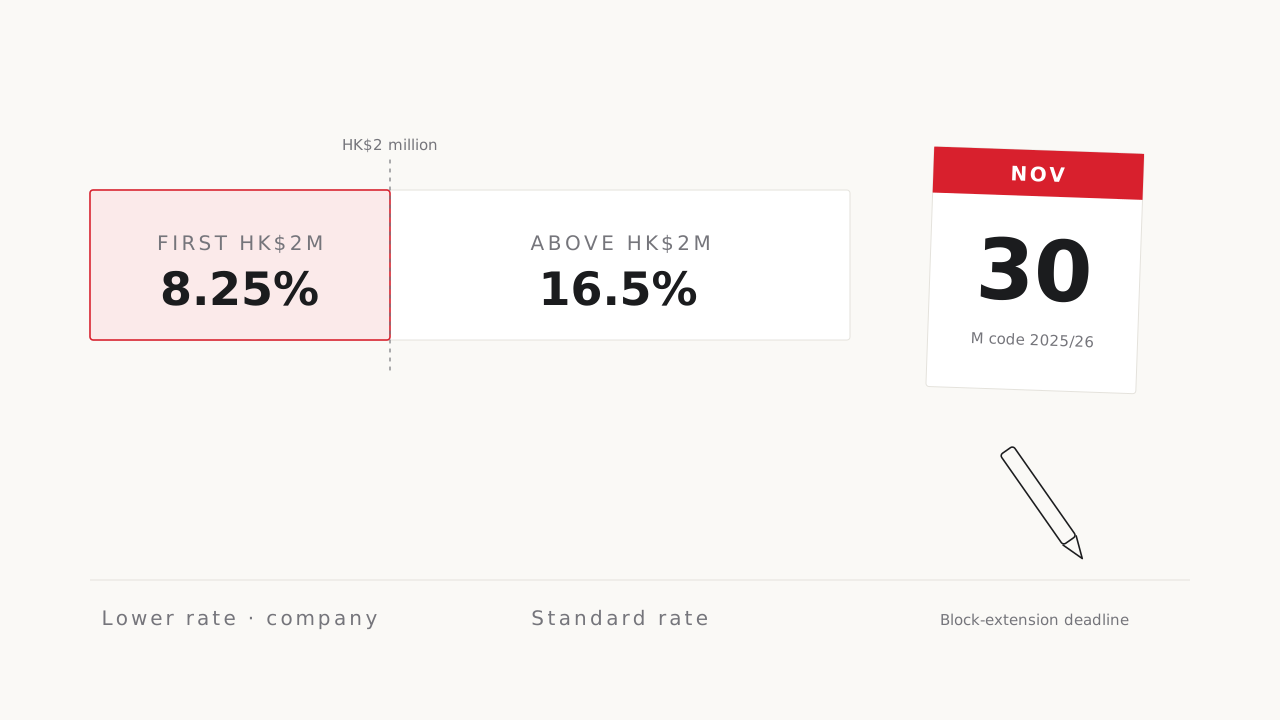
A limited company pays profits tax at 8.25% on its first HK$2 million of assessable profits and 16.5% on the rest. Sole proprietors and partnerships pay 7.5% and 15%. A company with HK$3 million in profits pays HK$330,000, which is HK$165,000 less than at a flat 16.5%.
If a company has connected entities, only one of them can use the two-tiered rates in a year of assessment. For 2025/26, the block-extension deadline for M-code companies (year end January to March) is 30 November 2026.
Trust or Company Service Provider Licence TC010617 · Updated: November 2026
A limited company with HK$3 million in profits pays HK$330,000 in profits tax. At a flat 16.5% it would be HK$495,000. The HK$165,000 difference is the two-tiered regime.
What are the two-tiered profits tax rates?
The first HK$2 million of assessable profits is taxed at a lower rate, and the rest at the standard rate. The regime started in the 2018/19 year of assessment and is unchanged for 2026/27.
| Business type | First HK$2 million | Above HK$2 million |
|---|---|---|
| Limited company (corporation) | 8.25% | 16.5% |
| Sole proprietorship, partnership (unincorporated) | 7.5% | 15% |
A limited company saves at most HK$165,000 under the regime (HK$2 million × 8.25%). An unincorporated business saves at most HK$150,000.
How is profits tax calculated? Four examples
The rates apply to assessable profits, not to turnover or the accounting profit in your books. The accounting profit is first adjusted under the Inland Revenue Ordinance, for example by adding back non-deductible expenses.
| Assessable profits | Limited company tax | Sole proprietorship / partnership tax |
|---|---|---|
| HK$1.5 million | HK$123,750 | HK$112,500 |
| HK$2 million | HK$165,000 | HK$150,000 |
| HK$3 million | HK$330,000 | HK$300,000 |
| HK$5 million | HK$660,000 | HK$600,000 |
For a limited company with HK$5 million:
- First HK$2 million × 8.25% = HK$165,000
- Remaining HK$3 million × 16.5% = HK$495,000
- Total HK$660,000
The table ignores the HK$3,000 reduction for 2025/26. With it, a limited company with HK$1.5 million in profits pays HK$120,750 for 2025/26.
I have two companies. Can both use 8.25%?
Not if they are connected entities. In each year of assessment only one nominated entity can use the two-tiered rates. Every other connected entity pays the full 16.5% (15% if unincorporated).
Connection is about control. In general:
- one company controls more than 50% of another’s share capital, voting rights, capital or profits, directly or indirectly; or
- both companies are more than 50% controlled by the same person.
Two sole proprietorships owned by the same person are also connected. The nomination is made in the tax return and cannot be revoked for that year; a different entity can be nominated the following year.
This is the point most often missed. Before you open a second company, work out which one will make more profit and should use the two-tiered rates.
Is there a profits tax reduction for 2025/26?
Yes. Profits tax for the 2025/26 final assessment is reduced by 100%, capped at HK$3,000 per business. The legislation was passed on 13 May 2026 and gazetted on 22 May 2026.
The IRD applies the reduction when it issues the assessment; you do not need to apply. Two things to note:
- The reduction does not apply to provisional tax. Pay provisional tax as shown on your notice.
- No reduction has been announced yet for 2026/27.
When is the 2025/26 profits tax return due?
The IRD bulk-issued the 2025/26 Profits Tax Returns (BIR51) on 1 April 2026. The normal deadline is one month from the date of issue. Companies with a tax representative can use the block extension, grouped by year end:
| Code | Year end | Block-extension deadline | Electronic filing (if eligible) |
|---|---|---|---|
| N | 1 Apr – 30 Nov 2025 | 4 May 2026 | 4 June 2026 |
| D | 1 – 31 Dec 2025 | 31 August 2026 | 2 October 2026 |
| M | 1 Jan – 31 Mar 2026 | 30 November 2026 | 30 December 2026 |
| M (current-year loss) | Same, on application and approval | 1 February 2027 | 1 February 2027 |
The M-code deadline was originally 16 November. The IRD extended it to 30 November in a circular dated 20 October 2026.
Companies filing without a tax representative should follow the deadline printed on their return. A newly incorporated company usually receives its first return about 18 months after incorporation and must file it within 3 months of the date of issue.
A limited company must file audited financial statements signed by a certified public accountant with its return. Allow 3 to 4 months after the year end for bookkeeping and the audit.
What happens if I file or pay late?
- Late return: the IRD may issue an estimated assessment. Without a reasonable excuse, the penalty on conviction is a fine of up to HK$10,000 plus 3 times the tax undercharged. Instead of prosecuting, the IRD may impose additional tax of up to 3 times.
- Late payment: a 5% surcharge is added to tax not paid by the due date, and a further 10% if it is still unpaid after 6 months.
- Records: business records must be kept for at least 7 years.
What is provisional tax? Can I pay less?
Provisional tax is an advance payment of the next year’s profits tax, usually estimated from the previous year’s assessable profits. Once the final assessment is issued, the provisional tax already paid is credited against it. It is normally paid in two instalments; the amounts and dates are on your notice.
If you expect this year’s assessable profits to be less than 90% of last year’s, you can apply to hold over part of the provisional tax. Apply at least 28 days before the due date, or within 14 days of the notice date, whichever is later. Until the application is approved, pay on time.
To set money aside for tax in advance, you can use tax reserve certificates. See What tax reserve certificates are for.
Limited company or sole proprietorship: which pays less tax?
On rates alone, sole proprietorships and partnerships pay less: 7.5% on the first HK$2 million against 8.25% for a limited company. A sole proprietor can also elect for personal assessment; a limited company cannot.
But tax is not the only factor in choosing a business structure. A limited company’s shareholders have limited liability, while a sole proprietor is personally liable for the business’s debts. A limited company also needs an audit and an annual return every year. Talk to us before you decide.
What to prepare before filing
- Confirm your year end and whether you are N, D or M code.
- After the year end, collect the year’s receipts, bank statements and invoices.
- Allow time for the audit by a certified public accountant.
- If you have connected companies, decide which one uses the two-tiered rates this year.
- Check your 2025/26 assessment includes the HK$3,000 reduction.
- File before the deadline and pay according to your notice.
Our accounting and tax service handles bookkeeping, audit and filing together. Questions? Contact us and we reply within 30 minutes.
Rates, deadlines and figures in this article reflect public information as at November 2026, from the IRD’s FAQ on two-tiered profits tax rates, the 2026–27 Budget tax measures, the 2025/26 block-extension circulars (19 March, 14 July and 20 October 2026) and the Inland Revenue Ordinance (Cap. 112). Laws, deadlines and fees may change; the IRD’s announcements and the return and notices you receive prevail. This article is general information, not tax or legal advice.